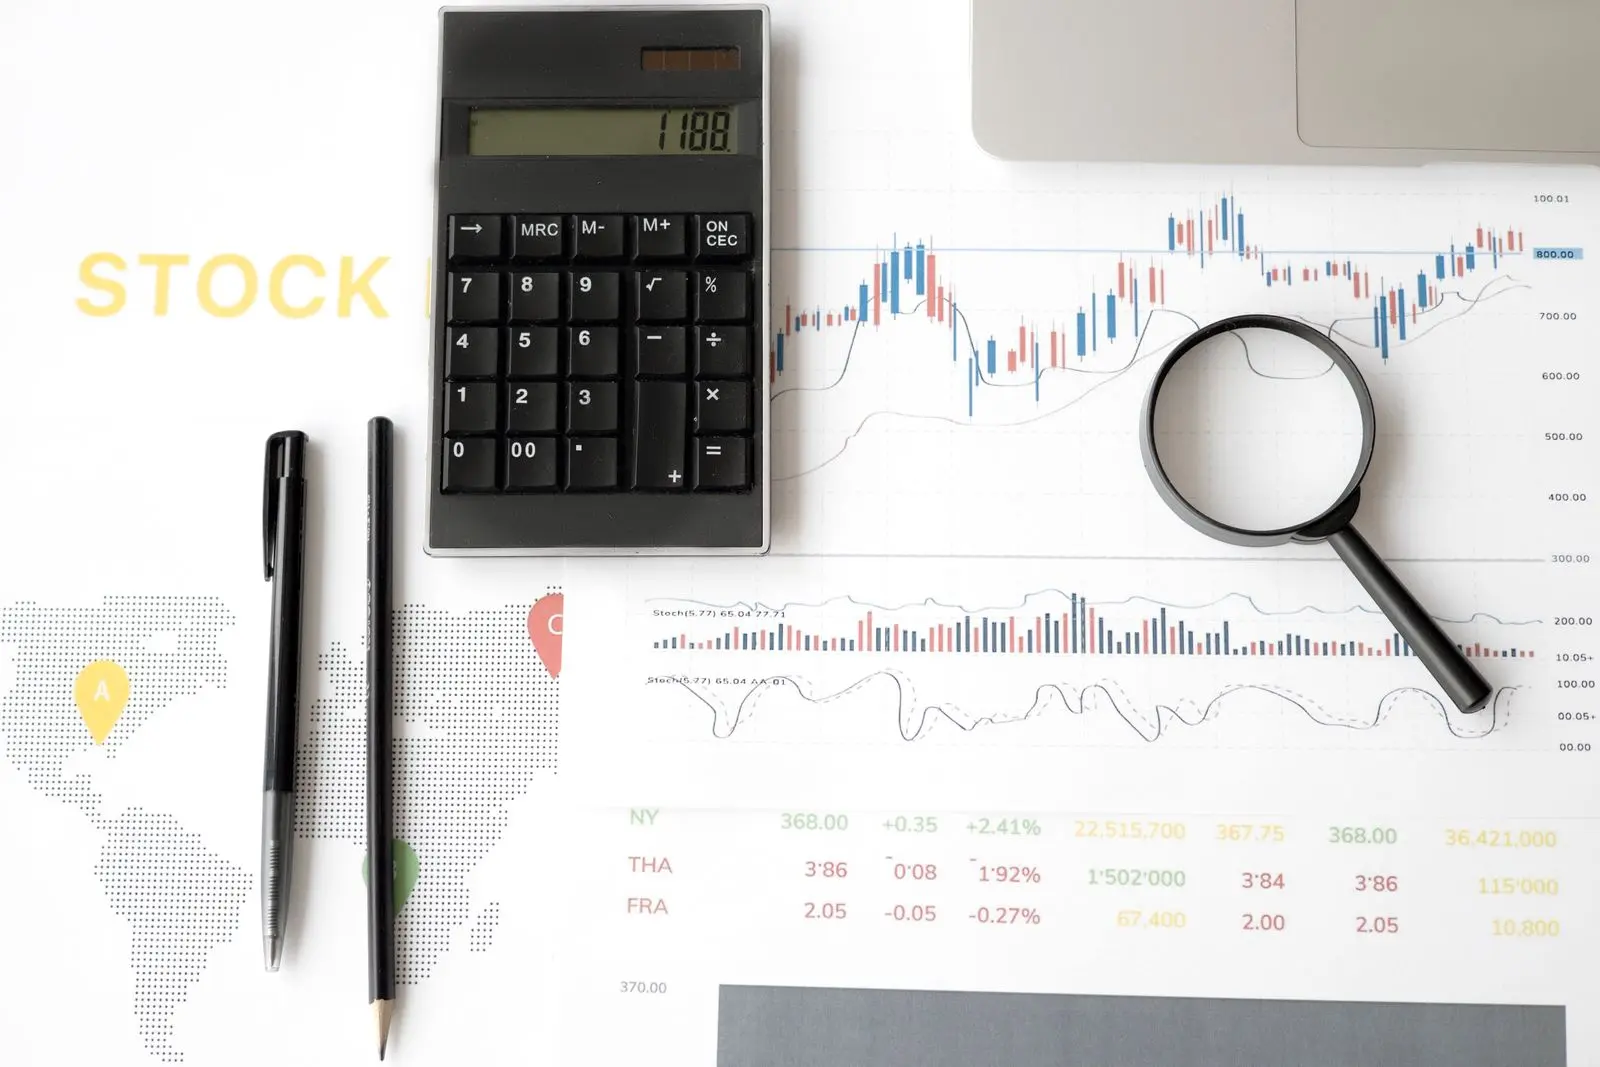
On Tuesday morning, JPMorgan Chase, Goldman Sachs, Citigroup and Wells Fargo report earnings before the open. On Wednesday, the September inflation report lands, and Bank of America and Morgan Stanley report the same morning. For a few hours, Wall Street gets its scorecard and the economy gets its thermometer at once.
Here is what the forecasts say, what could go wrong, and which number I would actually read first.
The calendar
Based on two weekly previews, the schedule looks like this:
- Tuesday, October 13 (before the open): JPMorgan, Goldman Sachs, Citigroup and Wells Fargo.
- Wednesday, October 14: September CPI, plus Bank of America and Morgan Stanley (and BlackRock, per one preview) before the open.
- Thursday and Friday: regional lenders including PNC, U.S. Bancorp, Charles Schwab and Truist.
- October 27-28: the next Federal Reserve meeting.
One preview from FXEmpire pegs JPMorgan’s earnings-per-share forecast at $5.93 and Goldman’s at $13.04. A Stocktwits preview shows different consensus numbers ($5.95 for JPMorgan, $14.84 for Goldman), so estimates vary by data provider. Treat any single figure as approximate.
What the inflation forecasts say
The FXEmpire preview lists the consensus for the September consumer price index as follows:
- Headline CPI: up 0.6% for the month (prior month 0.4%) and 3.6% from a year earlier (prior 3.4%).
- Core CPI, which strips out food and energy: up 0.2% for the month (prior 0.3%) and 2.5% from a year earlier (prior 2.4%).
Stocktwits, citing a Dow Jones estimate, shows a slightly different annual headline forecast of 3.7%, with the same 0.6% and 0.2% monthly figures. The release time cited by FXEmpire is 12:30 GMT, which is 8:30 a.m. Eastern.
Notice the gap. A headline reading of 0.6% alongside a core reading of 0.2% suggests that food and energy are doing most of the work. Oil was trading around $91 a barrel on Friday morning, according to a Schwab market update, which fits that picture. That link is my inference, not something either preview states.
Why the Fed is the real audience
The Federal Reserve raised interest rates in September, its first increase since 2023, according to a TradingKey summary of the meeting minutes, which also reported a unanimous vote and a new range of 3.75% to 4%. The same summary said expectations for an October hike had fallen below 20%.
The FXEmpire preview adds the other side: a hotter-than-expected CPI report could revive bets on an October move. Traders are also watching Fed speakers, including Governor Kevin Warsh on Thursday, and the Beige Book.
So Wednesday’s number does more than describe last month. It shifts the odds on what the Fed does on October 28.
The earnings backdrop is strong, with an asterisk
Schwab, citing FactSet, said analysts expect third-quarter earnings growth of 29.5% for S&P 500 companies, and that 72 companies had issued positive guidance, the most since FactSet began tracking it in 2006. FXEmpire’s preview describes expectations for growth above 30%.
That is a high bar. The S&P 500 closed last week at 7,811.54 and the Nasdaq Composite at 27,366.17, both near record highs, according to the FXEmpire preview. When prices already reflect strong results, the reaction depends on guidance and tone, not on beating the number.
Schwab’s recap of Thursday’s selloff makes the same point. Samsung reported nearly a ninefold rise in quarterly profit, and its stock is still about 25% below its June high, according to that recap. Taiwan Semiconductor reported 51% sales growth, and its stock fell too.
What a surprise would look like
Consider the two ways Wednesday can break from the forecast. If headline CPI comes in above 0.6%, the story becomes energy costs spreading, and the odds of another Fed hike would likely rise, since the FXEmpire preview ties a hotter report to revived October bets. If core CPI prints above 0.2%, that points to price pressure outside food and energy, which is the kind of inflation central bankers worry about most.
A cooler core number would do the opposite. It would give the Fed room to wait, and it would take some pressure off borrowing costs. These are scenarios, not predictions, and a single month of data rarely settles a trend.
Why banks matter for this particular print
Bank earnings are the closest thing the market has to a live read on borrowers. FXEmpire’s preview says the reports will show how higher rates and energy costs are affecting consumers and capital markets.
Two lines in each bank’s results deserve a look. The first is the provision for credit losses, the money a bank sets aside for loans that might go bad. The second is what executives say about consumer spending and loan demand on the earnings call. Neither appears in the headline earnings-per-share figure, and both say more about the next two quarters than the beat or miss does.
A sidebar for anyone shopping for a mortgage
If you are thinking about a home purchase, this week matters directly. MortgageDaily reported that the 30-year fixed rate was about 7.42% on October 8, based on Optimal Blue data, with Freddie Mac’s survey at 7.40%. The same article says lenders were keeping wide margins over the 10-year Treasury ahead of the CPI report, and that a cooler print could ease pricing while a hotter one could add pressure. That article had some internal inconsistencies, so check the figures against Freddie Mac and your lender’s own quote.
When I think about home buying in general terms, what stands out is how little notice a rate move gives you. A quote you were given Monday can look different by Thursday.
My take: ignore the 0.6%
Headlines on Wednesday will probably lead with the biggest number, and if the forecast holds, that is the headline CPI. My view is that core CPI and the banks’ credit-loss provisions tell you more about where this goes next.
If core comes in near 0.2% and banks sound calm about consumers, the energy-driven spike looks like a temporary push on prices, and the October Fed meeting stays quiet. If core jumps while banks start setting aside more for bad loans, that is a very different week.
Watch those two lines first. The headline can wait.