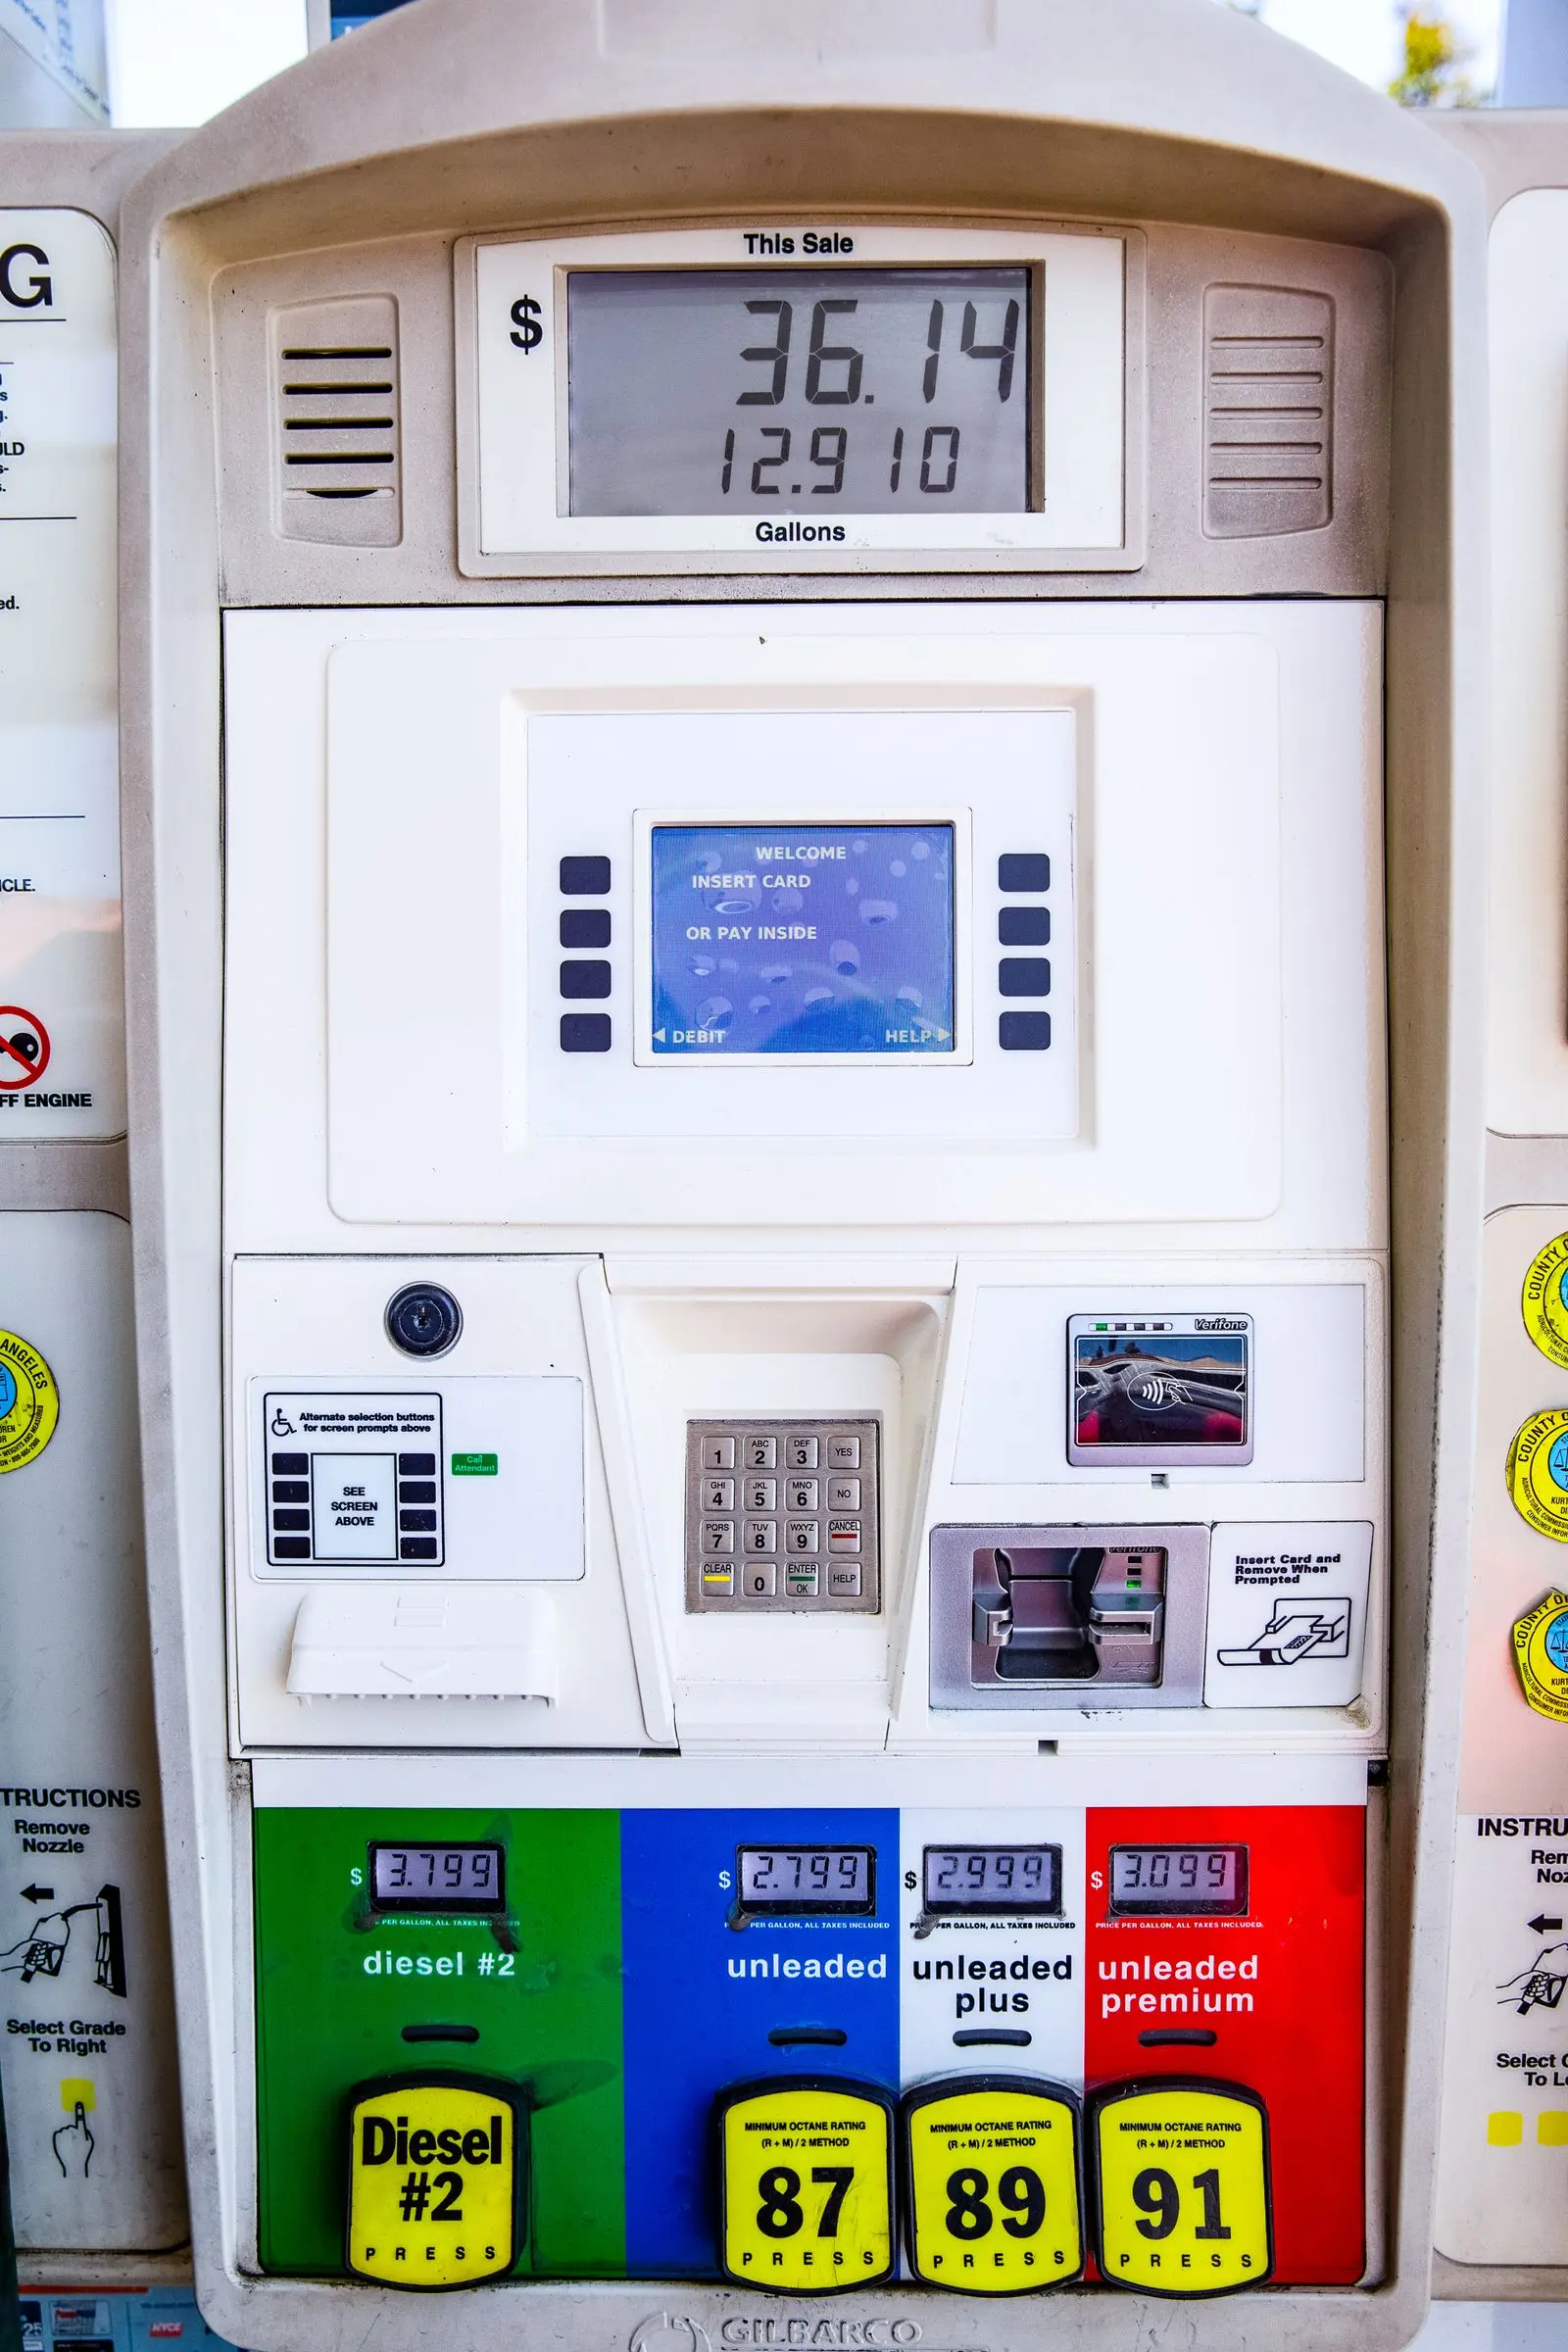
Gasoline did most of the damage in September’s inflation report. The part households should worry about is what showed up outside the gas station.
The Labor Department’s September Consumer Price Index rose 0.6% from August and 3.7% from a year earlier, up from 3.4% in August and above the 3.6% economists expected, according to Yahoo Finance and The Mortgage Reports. Within a day, traders had roughly doubled their bet that the Federal Reserve raises interest rates again at its October 28 meeting.
The numbers behind the headline
Energy was the main driver. Gasoline jumped 9.1% in the month and accounted for more than half of the headline increase, per The Mortgage Reports. Yahoo Finance adds that fuel oil rose 15.3%.
Economists usually look past energy to core CPI, which strips out food and energy. Core rose 0.3% on the month, against the 0.2% forecast, and 2.6% over twelve months, up from 2.4% in August and a five-year low. Capital Economics’ Stephen Brown said the upside surprise was broad-based rather than tied to obvious one-off factors, as quoted by Yahoo Finance. That matters because the Fed treats broad strength differently from a single spike at the pump.
Shelter, the largest household cost, rose 0.4% after a 0.3% gain in August, according to The Mortgage Reports. Owners’ equivalent rent, a gauge of what homeowners would pay to rent their own homes, rose 0.3%.
Paychecks are losing ground
Pay did not keep up. Average hourly earnings rose 0.1% in September and 3% over the year, Yahoo Finance reported, which means inflation is outrunning wages. Real average hourly earnings fell 0.7% over the past year. Heather Long, an economist at Navy Federal Credit Union, described the squeeze as lasting six months, as quoted by Yahoo.
The same report includes one offsetting number for retirees: Social Security’s 2027 cost-of-living adjustment is 3.6%, about $75 more per month on average, per Yahoo Finance. That is a headline raise, and the Medicare premium deducted from it will decide what actually lands in the bank account.
The Fed’s October question
The Fed’s target range is 3.75% to 4.00% after a September increase, its first in three years. Before the CPI report, CME FedWatch priced about a 22% chance of another quarter-point hike on October 28. By Wednesday morning, October 14, that was 43.7%, per The Mortgage Reports and Yahoo Finance. Yahoo adds that markets saw better than even odds of a second hike by December.
Officials sounded cautious. Chicago Fed President Austan Goolsbee called the reading discouraging but said he wanted more data before acting, according to Yahoo Finance. Wolfe Research’s Stephanie Roth said committee members would very much prefer not to raise rates in October. The Mortgage Reports reports that New York Fed President John Williams is said to expect no hikes in 2027 and to see room for one more increase this year; that is a single-source, secondhand characterization and should be treated accordingly.
The meeting runs October 27 to 28. The next big data point is the PCE price index on October 29, the Fed’s preferred inflation gauge. The following meeting is December 8 to 9, and September minutes showed most officials expect another increase by year-end, The Mortgage Reports says.
Why your mortgage quote may not follow the Fed
The Fed does not set mortgage rates, and that point is easy to lose in a week like this. A 30-year mortgage tends to track the 10-year Treasury yield, not the Fed’s overnight rate. The 10-year closed at 5.21% on October 13, down from a recent high of 5.31% on October 5, per Mortgage Daily, and traded around 5.24% to 5.3% after the CPI release.
Published mortgage averages vary because each measures something different:
- Freddie Mac’s weekly survey showed 7.40% on October 8, with the next reading due Thursday, October 15.
- The Mortgage Bankers Association put its 30-year contract rate at 7.50% for the week ending October 9.
- Optimal Blue’s index was 7.36% on October 13, per Mortgage Daily.
- Mortgage News Daily had rates up 10 basis points to 7.56% after the CPI release, as cited by Yahoo Finance.
The 52-week range in Mortgage Daily’s data runs from 5.90% on February 27 to a high of 7.46% on October 5. The MBA reported mortgage applications fell 2.7% in the latest week.
What a small move costs
The Mortgage Reports offers an illustration: on a $400,000, 30-year fixed loan, 7.28% versus 7.38% works out to about $2,737 versus $2,764 a month, roughly $27 more, or $327 a year, for principal and interest only. A tenth of a point is real money but not a catastrophe. A full point is another story.
Rate locks matter more than most shoppers expect. Until a rate is locked, a quote floats with the market. Locks typically run 30 to 60 days, and a locked rate generally holds if the loan closes before the lock expires and the borrower meets its conditions.
What to watch next
For households the practical read is simple. Inflation running at 3.7% against pay growth of 3% means budgets are tighter than they were a year ago, and a Fed that keeps raising rates makes borrowing more expensive at the same moment. Credit card balances, adjustable-rate loans and any planned home purchase are the places where a higher-for-longer path shows up first. Savers, by contrast, may see better yields, though not enough to offset a price level that keeps climbing faster than wages.
Three checkpoints will decide how this plays out: the Freddie Mac reading on October 15, the PCE report on October 29, and the Fed’s decision on October 28. If core inflation keeps surprising upward, a second hike moves from possible to likely. If energy prices fade and core cools, the October scare may look like a blip.
Editor’s take
Having been through the home-buying process, I would not try to guess the Fed. I would watch the 10-year yield and the lock terms in a written quote. The headline rate on the news matters less than whether your lender will hold a number long enough for you to close. If you are shopping now, ask for lock length and any extension fees in writing, and compare quotes on the same day.